Modular card insurance in a banking app
Modular card insurance in the BTG+ banking app: customers choose their cover instead of buying a fixed bundle. I designed it and tested where to sell it; in the card request it put sign-ups at risk, so it sits in the card's settings.
- Role
- Senior Product Designer
- For
- BTG+ card customers
- What I did
- Survey
- Benchmark
- Flows
- Prototyping
- Usability testing
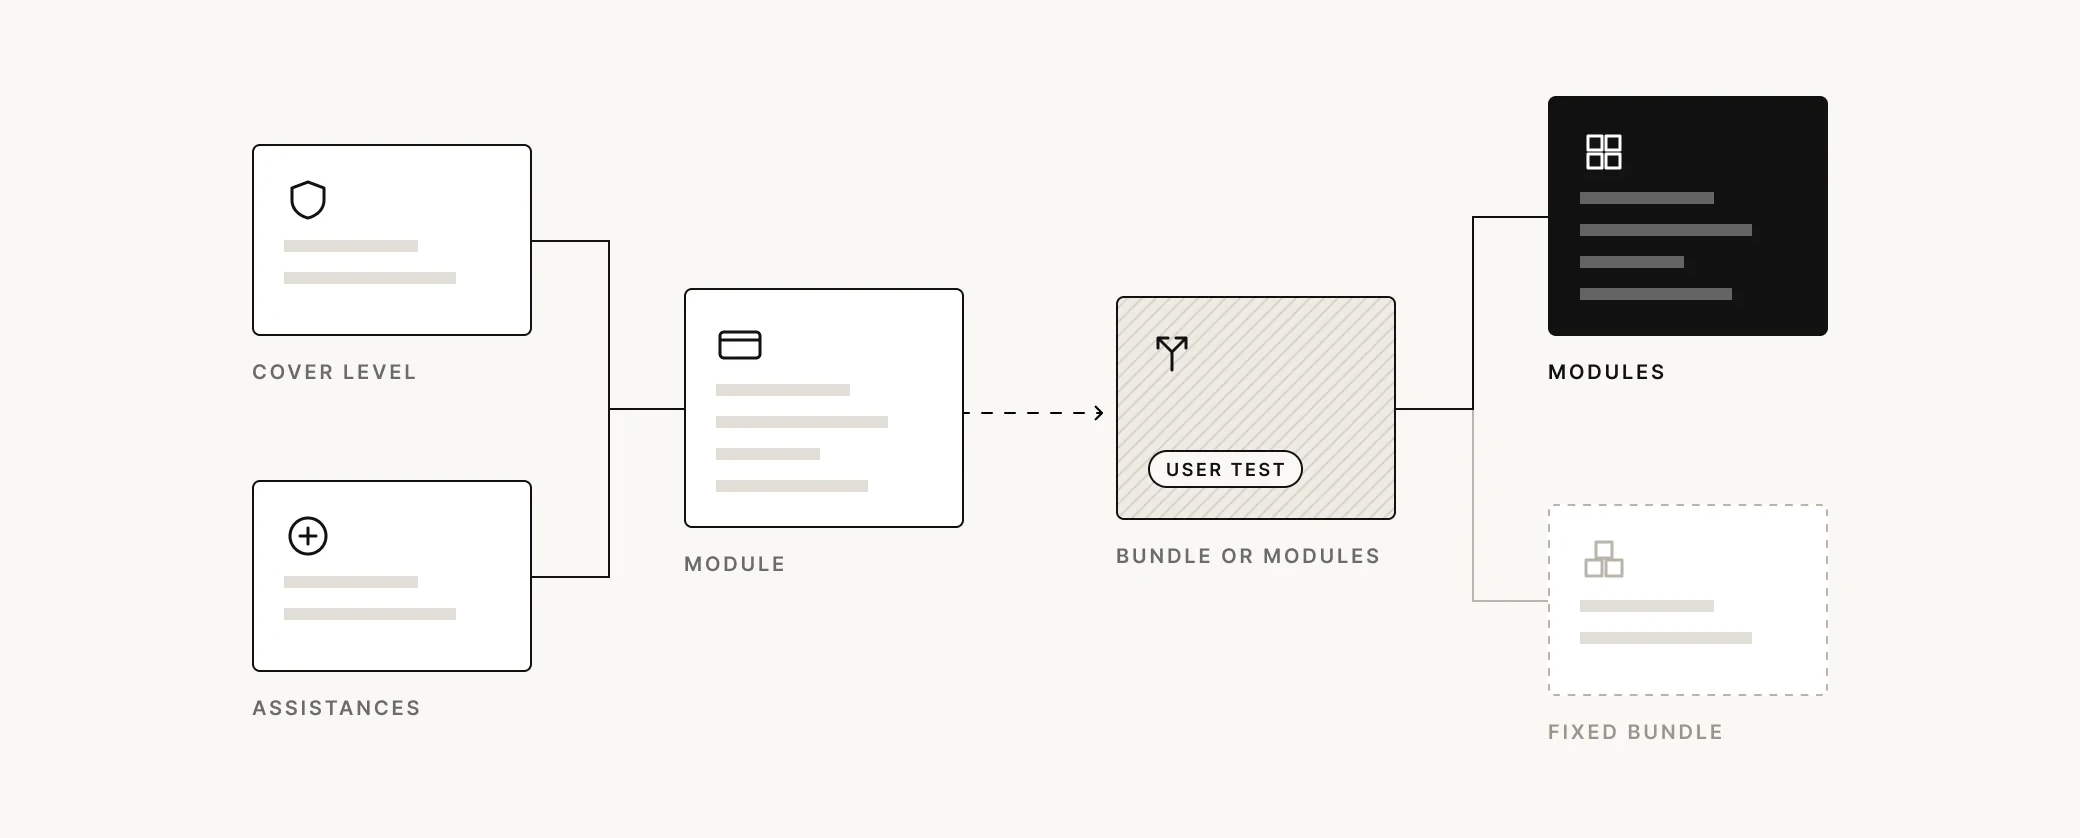
- Cover level and assistances
- Module
- Bundle or modules
- Modules and fixed bundle
01
What customers wanted
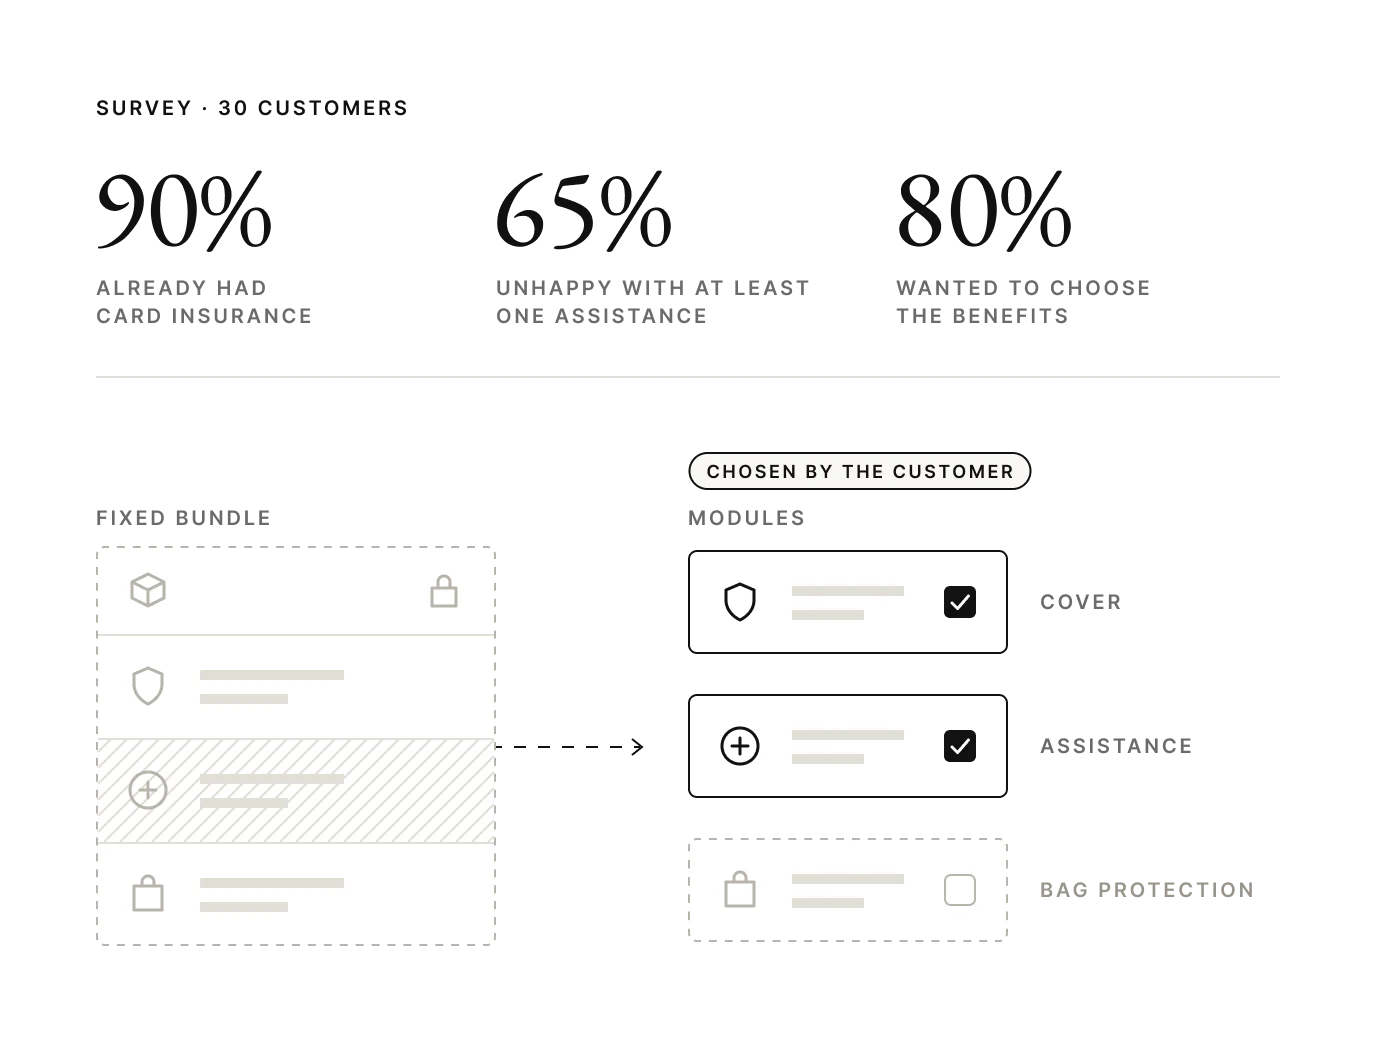
BTG Pactual was entering retail banking. I surveyed 30 customers: 90% had card insurance, 65% disliked at least one assistance in their package (a service such as home repairs), and 80% wanted to choose the parts.
In a fixed bundle, the limits are buried in policy clauses. Customers can't compare the parts or drop the ones they don't want.
02
The limits
The insurer, Too Seguros, set the cover, prices and claim rules, and regulated terms can't be reworded. So clarity had to come from layout: each limit next to the price. And card conversion was the retail business's key metric, so anything added to the card request put it at risk.
03
The design
With the PM, tech lead and developers, I agreed three principles first: simplicity, personalisation, transparency. Later disagreements were settled against them.
I reviewed seven insurers; three shaped the structure: Cuvva (the price updates as cover changes), Wrisk (a policy built one question at a time) and Lemonade (plain language). The customer picks one of three plans, then one free assistance: pet, repairs, home, emergency services or bike.
- Pick one free assistance
- Confirm the details
- Done
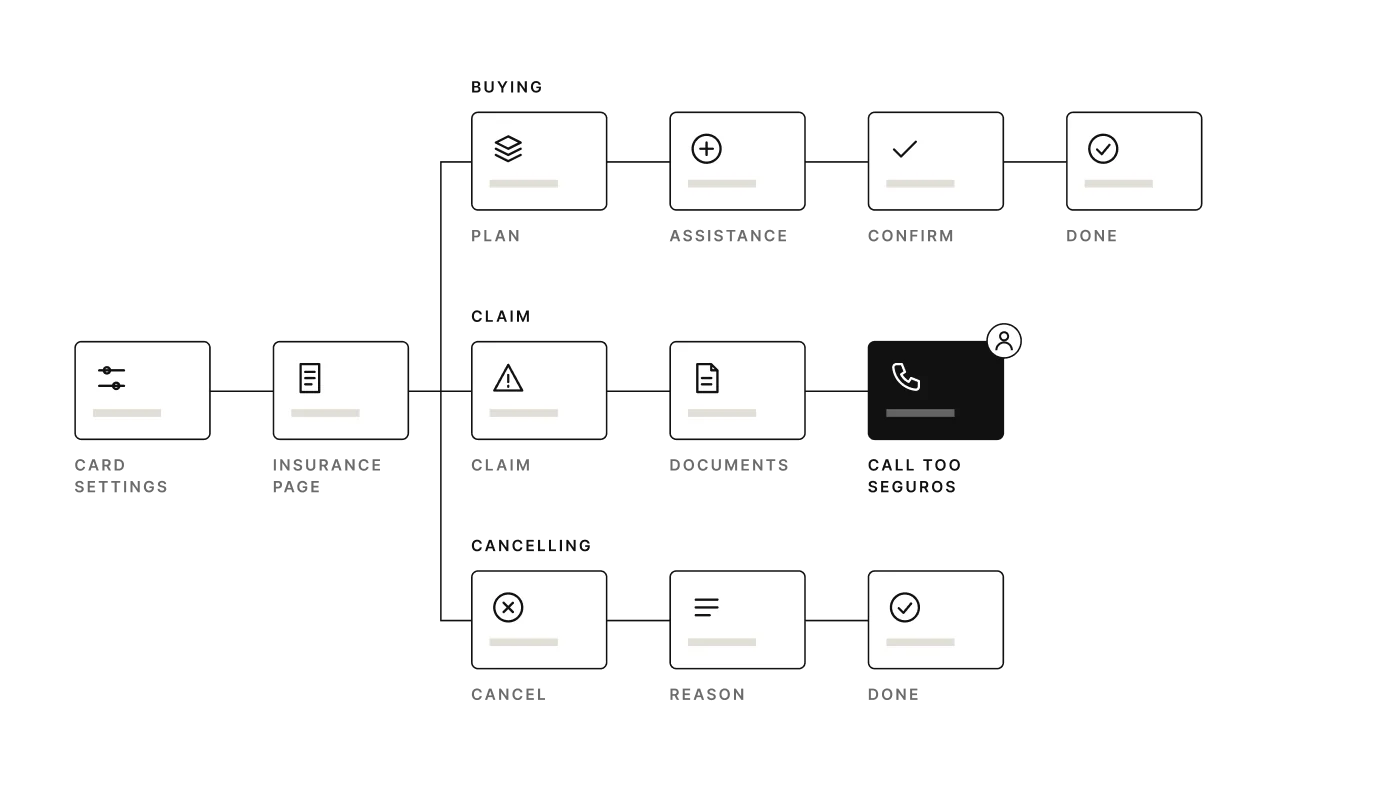
I designed all three flows: buying, claiming and cancelling. The claim is when customers learn if the insurance works.
04
The test
I tested both placements, in the card request and in the card's settings, with 10 customers. In the request, insurance made a crowded sign-up longer and mixed free and paid products in one checkout.
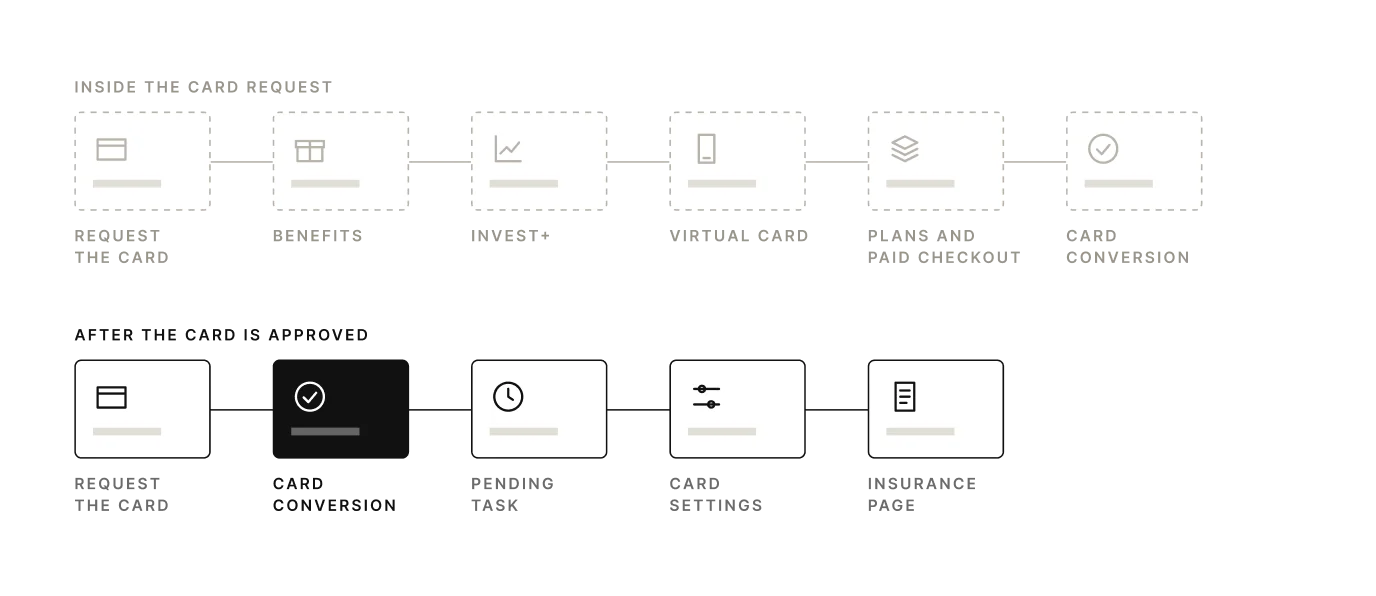
So we moved it. Once the card is approved, insurance appears as a pending task, with a permanent place in the card's settings.
- Open the card menu
- Tap Seguro do cartão
- The insurance page opens
Customers were slow to notice the price change between plans, so the price and limits now update in place.
- Switch to Pleno
- Switch to Superior
05
What I learned
Test where a feature sits, not only its screens
The screens worked in both places; the placement was the decision.
In regulated products, clarity comes from layout
The wording can't change, so what sits beside the price has to explain it.
Agree principles early
They let me argue for the move with rules engineering had already signed.
06
What this case doesn't cover
- Results after launch. I left before they were measurable.
- Prices. They were set by the insurer; the ones in the figures are placeholders.
- Accessibility. No review was run.
Next case
06 / 07Mesa Jurídica · 2026